Category Archives: Economics and Trade

Elemental Leverage: How the United States Can Stop China’s Rare-Earths Squeeze Before the Next Crisis

By Josh Richards and Joseph Hanacek

The Elemental Weapon

When China threatens to close its fist, the world listens. In August 2025, Li Chenggang, Beijing’s chief trade negotiator, didn’t bother with euphemism. If the United States continued tightening controls on advanced technologies, he warned, China would answer by restricting exports of the metals that make those technologies possible.1 Rare-earth elements, the invisible foundation of jet engines, electric vehicles, and precision weapons, had become bargaining chips in a new kind of power game.

It was a small statement with continental consequences. Within weeks, Chinese ministries began slowing export licenses for certain alloys and magnetic materials, sending nervous tremors through markets from Tokyo to Detroit. The message was unmistakable: what Washington thinks of as global supply chains, Beijing sees as instruments of leverage.

That moment captured the logic of the age. Over the last two decades, the United States and its allies treated the materials that underpin modern life, rare-earths such as lithium and cobalt as the anonymous plumbing of globalization. China treated them as strategy. Today it controls most of the world’s processing and virtually all of the stages that matter: refining, separation, and magnet manufacturing. In total, Beijing controls roughly 70 % of global mining, about 90 % of separation/processing, and more than 90 % of high-performance magnet manufacturing.2 The result is an asymmetry more dangerous than most weapons systems because it operates quietly, through dependency rather than force.

This is not simply a rehearsal for war over Taiwan and the global semiconductor market, though that flashpoint looms over everything. It is part of a broader campaign to reorder the global balance of power, to remind every nation that in the 21st century, the flow of materials can be as decisive as the movement of troops. Rare-earths have become Beijing’s favorite pressure point because they embody the new reality of competition: the next crisis may begin not in the Taiwan Strait, but in a factory that can no longer get the magnets it needs.

And yet, the story is not just about China’s dominance, it is about America’s choices. Whether the United States treats this as a passing market fluctuation or a defining national-security test will determine not only its industrial resilience, but its ability to deter coercion before a single shot is fired.

The Strategic Context: Material Leverage in a Post-Industrial Age

Beijing’s threats over rare-earth exports are not a sudden innovation; they are the predictable evolution of a decades-long strategy. China benefits from low-cost mining and lax environmental regulation, but their dominance in rare earth elements did not emerge purely from geological luck. Rather, China employed deliberate statecraft, leveraging industrial policy fused with geopolitical vision. Since the late 1990s, the Chinese government has poured billions into refining, separation, and magnet-making infrastructure, while the United States dismantled its own. By the 2010s, Beijing had learned to turn economic scale into political leverage: subsidize the middle of the supply chain, flood global markets, drive out competitors, and then consolidate control. What began as a commercial edge became a coercive instrument. 3

The results are stark. China now accounts for the overwhelming majority of global rare-earth processing and nearly all of the world’s high-performance magnet production—the beating heart of everything from precision weapons to renewable-energy systems. In a global economy where advanced technologies are the currency of power, control of materials is control of tempo. Beijing understands this intimately. Its 2023 export-control laws, followed by tightened magnet licensing in 2025, were not about profit; they were about signaling. 4 Each new bureaucratic delay or “security review” serves as a reminder that dependency is a policy choice, and that global markets operate at China’s discretion. 5

For the United States, this is not merely an economic vulnerability—it is a strategic liability. Every day that the refining, alloying, and magnet-making that feed America’s defense and technology sectors remain concentrated overseas, Washington’s deterrent posture weakens. The lesson is familiar to anyone who watched Russia’s manipulation of Europe’s gas supply in 2021: energy dependence and material dependence both collapse deterrence long before the first crisis erupts.

Why the U.S. Can’t Wait for Taiwan

It is tempting to treat China’s tightening grip on rare-earths as a prelude to war over Taiwan, a crisis to be managed “when the time comes.” That would be a mistake. The rare-earth squeeze is already here, unfolding in boardrooms and customs ports rather than battlefields. The August 2025 remarks from Li Chenggang were not idle bluster. They marked a deliberate escalation in Beijing’s campaign to use industrial interdependence as leverage, an offensive waged through permits, tariffs, and export licenses instead of missiles. 6

Beijing’s logic is simple and effective: coerce early, not late. By testing Western vulnerabilities before open conflict, China forces companies and governments into self-censorship and hesitation. It pressures investors to think twice about U.S. manufacturing projects and signals to allies that Washington cannot protect their supply chains. In other words, the weaponization of trade happens during peacetime precisely because it is more efficient than war.

Yet this economic coercion is not separate from Beijing’s territorial ambitions, but a prelude to them. The same strategic vision that seeks dominance in the Taiwan Strait also seeks dominance in the global flow of strategic materials. In both cases, the goal is the same: to make resistance costly and compliance inevitable.

If the United States waits for a military crisis to address these dependencies, it will have already lost the contest that matters most over industrial sovereignty. A credible response must begin now, while the tools of competition are still commercial and the battlefield still economic. The coming decade will test whether Washington can rewire its supply chains faster than Beijing can weaponize them.

The question of how to outmaneuver China is not abstract, but physical: how to rebuild the industrial arteries that power American strength. The contest over rare earths is a contest over the tangible ingredients of deterrence, the metals inside every jet, missile, motor, and microchip. What Beijing has achieved through decades of patient investment is not just control of markets but control of manufacturing tempo. To understand why this matters, and how deeply it runs through the U.S. economy, one must look beneath the headlines of trade disputes and into the machinery itself: where magnets, alloys, and sensors meet strategy.

Where the U.S. (and Allies) are Exposed

The United States’ advanced-technology economy is built on foundations most citizens never see and fewer understand. Every modern instrument of power, whether a fighter jet banking over the Pacific, a hypersonic missile guiding at Mach 5, an electric vehicle gliding through traffic, or a smart phone depends on the same microscopic ingredients: rare-earth elements. Neodymium, praseodymium, dysprosium, and terbium are not household names, but they are the metals that turn electrical energy into movement and precision. They make magnets that can survive the heat of jet engines, sensors that can detect the faintest electronic signals, and motors that spin with unmatched efficiency. When the ability to mine, refine, and magnetize those materials sits almost entirely overseas, dependency becomes a design flaw and a geopolitical risk. A shortage wouldn’t just slow production; it would stall entire defense and clean-energy programs at once.

The vulnerability lies not only at the start of the chain where ore is mined, but more critically in the middle, where those ores are refined, separated, and transformed into alloys and magnets. This “midstream” is where complexity, not geology, determines control. The United States can mine all the raw material it wants, but if it must still send concentrates overseas for separation or metallization, it remains at the mercy of those who own the processing plants. The Mountain Pass Mine in California illustrates the dilemma perfectly. It sits atop one of the world’s richest rare-earth deposits and can produce thousands of tons of concentrate each year, yet for much of its modern history those concentrates were shipped abroad to China for processing. Even as domestic separation resumes, the legacy of dependence lingers: until the U.S. can transform raw ore into finished magnets within its own industrial base, its security rests on someone else’s permits.

Analysts warn that even as mining diversifies, with new projects in Australia, Canada, and parts of Africa coming online, the choke point has simply shifted downstream. The “systemic trade risk,” as researchers call it, now clusters around the intermediate tiers: the solvent-extraction circuits that separate individual elements and the precision magnet plants that turn them into usable parts. China holds dominance over both.7 These are capital-intensive, chemically complex, and environmentally sensitive operations that Beijing spent decades perfecting and subsidizing while Western economies outsourced them. The United States today may have more mines in motion than ever before, but its midstream, the critical infrastructure for processing and magnet-making that turns geology into power remains fragile. Without it, every ton of ore dug in Nevada or Texas is still just another shipment waiting on a license from somewhere else.

A Strategic Blueprint: Five Interlocking Tracks

If the rare‐earth supply-chain shock is a plausible act of coercion, the U.S. must respond with a layered strategy. Here are five tracks—each reinforcing the others, each aimed not merely at mining more, but at transforming structural dependence into structural resilience.

A Strategic Reserve That Buys Time, Not Trophies. The United States doesn’t need a warehouse of geological curiosities—it needs a reserve that buys time in a crisis. That means stockpiling what defense and energy programs actually consume: refined oxides, metals, and magnets, rotated through active contracts to keep quality current. The reserve should function like an insurance policy, bridging weeks or months of disruption while diplomacy and supply adjust. Time, not tonnage, is its true measure. 8

An Allied Sourcing Compact. The path to resilience runs through partners. Australia’s separation plants, Canada’s deposits, Japan’s precision engineering, and Vietnam’s emerging reserves all form a foundation for shared security—if bound together by long-term offtake agreements and reciprocal release protocols. The Minerals Security Partnership already convenes these players; what’s missing is teeth. A formal compact—backed by price floors and clear crisis procedures—would convert goodwill into capacity. 9

Finishing the Middle at Home. America’s rare-earth story cannot end at the mine gate. True independence depends on the midstream—refining, separation, and magnet fabrication. Federal incentives through the Defense Production Act and DOE’s loan programs must target this stage, where every new processing line multiplies the effect of every new mine. Shared “tolling” facilities could let smaller miners buy processing services rather than build redundant plants, creating an ecosystem rather than a patchwork of projects. 10

Permitting That Moves at Strategic Speed.
Time is the ultimate enemy. A mine that takes ten years to permit is a strategic liability. The solution isn’t cutting corners—it’s aligning process with purpose: single-agency coordination, concurrent reviews, and designated industrial corridors with infrastructure in place. Projects that meet the highest environmental and community standards should move fast because they meet them, not despite them.

Recycling and Substitution That Close the Loop. America’s next rare-earth supply may come not from mountains but from scrapyards. Every retired wind turbine, EV motor, and hard-drive array contains magnets rich in recoverable material. A national recycling framework—paired with research into lower-dysprosium magnet designs—can reclaim what would otherwise be waste. Substitution doesn’t eliminate dependence overnight, but it bends the curve, turning scarcity into opportunity. 11

Rare-earth projects die in the troughs. Contracts-for-difference, floor-price puts, and anchored offtakes are not industrial charity; they are anti-whiplash technologies that make private capital rational. Pair those tools with Export-Import Bank and DFC support for allied projects in exchange for delivery rights, and suddenly the spreadsheet’s “downside case” looks financeable. The effect is cumulative: every financed separator or magnet line reduces the premium Washington pays for emergency barrels of oxides later.

A Phased Timeline

The first phase should begin immediately, focusing on shock absorbers rather than monuments. Within a year, the U.S. could establish a functioning Strategic Rare Earths & Magnets Reserve, buying and rotating modest quantities to work out logistics, and negotiate ten-year offtake and stock-swap agreements with close allies like Australia and Canada. These are achievable within existing authorities and budgets. At the same time, Washington should channel current Defense Production Act and Department of Energy funding toward the midstream: separation, metallization, and magnet lines that are already half-built. The goal is not to design new programs but to finish those that exist, turning ribbon-cuttings into production runs. Finally, a Five Eyes–EU monitoring cell should start quarterly stress-tests, with dry runs for a 90-day licensing freeze so that when friction appears in a port or a ministry, policymakers see it before procurement officers feel it.

The second phase, spanning roughly two to three years, must consolidate what the first began. Domestic refining and magnet lines should transition from pilot to full-scale operation, the reserve should grow into a buffer measured in months of defense and grid demand, and allied offtakes should begin steady delivery. This is also when recycling must move from experiment to infrastructure, with federal procurement preferences creating a guaranteed home for recycled content. On the regulatory side, the first industrial parks and brownfield re-mining projects should clear the new permitting regime, signaling credibility to investors that timelines are finally predictable.

By years three through seven, America’s resilience becomes clearly visible. Allied supply chains mature; U.S. magnet production satisfies a majority of domestic needs; and the strategic reserve gives Washington options when China flexes its licensing power. At that point, the geopolitical logic changes: when Beijing threatens to tighten a licensing screw, markets still move, but U.S. production schedules remain steady.

Strategic Implications for the Indo-Pacific and Taiwan

Although this paper does not hinge on a Taiwan invasion, that scenario illuminates the stakes. Taiwan remains central to the U.S.–China competitive equation. If Beijing were to blockade or invade Taiwan, U.S. and allied capabilities will depend on magnets, sensors, propulsion systems, many of which rest on rare-earth chains. If now the U.S. enters crisis mode and cannot spin up magnet production or import alternatives, the tactical decisions in the Strait will be made under supply shock, not strategic coherence and once the US military’s supply of expensive high-end munitions is exhausted, replacement will be difficult if not impossible

Moreover, an early rare-earth crisis, whether linked to Taiwan or technology competition (AI, cyber, semiconductors), can blunt U.S. response before kinetic conflict begins. Therefore, the rare-earth strategy is less a “nice to have” and more a mission-critical enabler of defense and economic posture in the Indo-Pacific.

Cost, Risk, and the Iron Law of Trade Leverage

The scale of investment, though nontrivial, is modest compared to the cost of being caught unprepared. Billions of dollars over five years for a reserve, tens of billions over a decade for full mid-stream build-out. The risks: project cost overruns, permitting delay, price collapses, partner country policy shifts. Many commentators have noted the U.S. faces a “rare-earth delusion” if it assumes mines alone solve the problem.12

But the alternative risk is far greater: if China decides to throttle supply, the industrial base, defense production, and allied manufacturing face cascading effects. The cost of doing nothing, or doing too little, is catastrophic strategic leverage left in the hands of an adversary.

Making the Blueprint Real

Blueprints don’t move metal; politics does. The architecture for rare-earth resilience already exists; the challenge now is execution. Turning strategy into supply will require coordination across institutions that rarely move in sync: Congress, the White House, the private sector, allied governments, and the capital markets that finance them all. Each has a role that only it can play.

Congress must provide consistency where markets cannot. It can modernize the Defense Production Act to treat separation, metallization, and magnet-making as enduring national-security priorities, not emergency programs that expire with each appropriation cycle. Long-term procurement authority, multi-year funding, and statutory stockpile mandates would tell industry that the rare-earth effort will outlast the next budget fight.

The executive branch holds the levers of speed. The White House and its interagency partners can cut permitting timelines, streamline environmental reviews, and integrate the work of DOE, DOD, and Commerce under a single critical-materials coordinator. The Minerals Security Partnership should evolve from a diplomatic forum into an operational alliance, tasked with financing and synchronizing projects across allied supply chains.

Industry and finance are the builders. Public capital can launch projects, but private capital must scale them. To draw investment into a volatile sector, Washington should expand price-stabilization mechanisms, such as floor-price guarantees, offtake contracts, and export credit support, so investors can model predictable risk. Without those tools, every project remains a gamble on Beijing’s next export decree.

Allies can be force multipliers when relationships are properly balanced and maintained. Australia, Canada, Japan, Vietnam, and the EU already have the geology and the expertise; what they need is U.S. demand certainty and shared strategic planning. Reciprocal stockpile release agreements, joint procurement, and common standards for refining and magnets could convert fragmented national efforts into a collective shield against coercion.

Finally, the public sector, from state governments to research institutions, must fill the innovation gap. Recycling systems, magnet reclamation, and material substitution will determine whether this decade’s investments build independence or simply delay dependence. Federal and state coordination on industrial parks, tax credits, and workforce training can ensure that new facilities are not just built but sustained.

If there is a single lesson from recent history, it is that resilience is rarely won in crisis, it is built in advance, when the costs are political rather than existential. China’s command of rare-earths supply is not destiny; it is the product of time, will, and coordination. The United States can still match it, but only if it acts with the same discipline and purpose.

The next confrontation may not unfold in the Taiwan Strait but in a shipment log, a licensing bureau, or a factory floor. The question is whether Washington will treat the rare-earth race as a line item, or as the front line.

Conclusion

In the decade ahead, warfighting and deterrence will not only be determined by fleets, missiles, and satellites; they will be shaped by mills, magnets, alloys and processing lines. Here is the dilemma: the United States has for too long treated rare-earth elements as an economic commodity subject to market forces. China treats them as strategic infrastructure subject to Party control.

The good news: the U.S. still has time. The moment of kinetic conflict in the Taiwan Strait, or a wider Indo-Pacific war is not today. But the moment of supply shock may well come before. When it does, the margin between success and failure will likely be defined by how quickly the U.S., its industry and its allies can spin those magnets, feed those sensors, roll those motors. The bets made today on stockpiles, allied contracts, processing plants, recycling and permitting reform are not optional; they are structural.

Deterrence is not just about sending ships and jets. It is about ensuring the industrial base behind those systems is resilient, trusted and redundant. When the next adversary contemplates turning off the tap on rare-earths, the United States should be the one saying: go ahead, the supplies are already on deck, production lines are humming, and we have a plan B at the ready.

That is how you turn elemental leverage into resilience, and how you ensure that supply chains become part of our defense, not part of their coercion.

Josh Richards is the Chief Commercial Officer of Pacific Peering. He serves on the UN’s Joint Task Force on SMART Cables as a member of the Steering Committee, and chairs the Business Development Committee. He is a Security Fellow with the Truman National Security Project, a Tech Policy Fellow with the Aspen Institute, and a Senior Fellow with AI2030.

Joseph Hanacek is a Surface Warfare Officer in the United States Navy. He serves as a Warfare Tactics Instructor at the Surface Advanced Warfighting School detachment of the Naval Surface and Mine Warfighting Development Center in San Diego, CA. The views and opinions presented herein are those of the author and do not necessarily represent the views of the Department of War, the Department of the Navy, or its components.

References

1. Hidayat, Muflih. “China’s New Rare Earth Export Controls: Global Supply Chain Impact.” Discovery Alert, October 16, 2025 https://discoveryalert.com.au/news/china-rare-earth-export-controls-2025-impact/

2. Baskaran, Gracelin. “China’s New Rare Earth and Magnet Restrictions Threaten U.S. Defense Supply Chains.” Center for Strategic and International Studies, October 9, 2025 https://www.csis.org/analysis/chinas-new-rare-earth-and-magnet-restrictions-threaten-us-defense-supply-chains

3. Klimek, Peter, Sophia Baum, Markus Gerschberger, and Maximilian Hess. “Systemic Trade Risk Suppresses Comparative Advantage in Rare Earth Dependent Industries.” arXiv, August 1, 2025 https://arxiv.org/abs/2508.00556

4. Baskaran, Gracelin. “China’s New Rare Earth and Magnet Restrictions Threaten U.S. Defense Supply Chains.” Center for Strategic and International Studies, October 9, 2025 https://www.csis.org/analysis/chinas-new-rare-earth-and-magnet-restrictions-threaten-us-defense-supply-chains

5. Reuters. “China Expands Rare Earths Restrictions, Targets Defense and Chips Users.” Reuters, October 9, 2025 https://www.reuters.com/world/china/china-tightens-rare-earth-export-controls-2025-10-09/

6. Hidayat, Muflih. “China’s New Rare Earth Export Controls: Global Supply Chain Impact.” Discovery Alert, October 16, 2025 https://discoveryalert.com.au/news/china-rare-earth-export-controls-2025-impact/

7. Klimek, Peter, Sophia Baum, Markus Gerschberger, and Maximilian Hess. “Systemic Trade Risk Suppresses Comparative Advantage in Rare Earth Dependent Industries.” arXiv, August 1, 2025  https://arxiv.org/abs/2508.00556

8. Baskaran, Gracelin. “China’s New Rare Earth and Magnet Restrictions Threaten U.S. Defense Supply Chains.” Center for Strategic and International Studies, October 9, 2025 https://www.csis.org/analysis/chinas-new-rare-earth-and-magnet-restrictions-threaten-us-defense-supply-chains

9. Kozul-Wright, Alex. “Can Australia Provide US with Rare-Earth Metals Which China Has Restricted?” Al Jazeera, October 17, 2025 https://www.aljazeera.com/news/2025/10/17/can-australia-provide-us-with-rare-earth-metals-which-china-has-restricted

10. Baskaran, Gracelin. “China’s New Rare Earth and Magnet Restrictions Threaten U.S. Defense Supply Chains.” Center for Strategic and International Studies, October 9, 2025 https://www.csis.org/analysis/chinas-new-rare-earth-and-magnet-restrictions-threaten-us-defense-supply-chains

11. Cameron, Hugh. “China’s Rare Earth Restrictions Could Backfire on Xi. Here’s How.” Newsweek, October 16, 2025 https://www.newsweek.com/chinas-rare-earth-restrictions-could-backfire-on-xi-heres-how-10886552

12. Foroohar, Rana. “America’s Rare Earth Delusion.” Financial Times, October 19, 2025 https://www.ft.com/content/583abbd2-ffa8-4232-931f-66f55949b5d5?syn-25a6b1a6=1

Featured image: An open-pit mine in Kokpatas, Uzbekistan, operated by Navoi Mining and Metallurgical. (Photo by U.S. Army Acquisition Support Center)
Asymmetric Spending: Taiwan’s Opportunities to Defend Against Economic Warfare

By Joseph Hanacek and Josh Richards

Recent events in the Strait of Hormuz offer a timely reminder that economic warfare at sea rarely resembles the clean, declared naval cordons of the past. Blocking commercial shipping from transiting through one of the world’s most critical energy arteries has not required mass sinkings or a total closure. Instead, a combination of selective strikes, vessel harassment, insurance volatility, and uncertainty has been sufficient to disrupt traffic, reroute ships, and impose real economic costs. In many cases, ships do not need to be sunk to be stopped; owners, insurers, or crews need only to decide that continuing forward is no longer worth the risk.

This emerging pattern reflects a broader shift in how maritime coercion is exercised, and is directly relevant to Taiwan, where Beijing is developing a range of coercive options: from incremental pressure on commercial shipping to high-intensity operations designed to rapidly sever Taiwan’s external lifelines. This was made abundantly clear in late December 2025, when the People’s Liberation Army (PLA) of China staged its most geographically expansive and strategically audacious military exercises around Taiwan in years.1 Over two days, the PLA mobilized warships, fighter jets, bombers, missile units, unmanned aerial vehicles, and coast guard elements across multiple designated zones in the Taiwan Strait and adjacent waters, focusing in particular on the island’s major ports, including Keelung in the north and Kaohsiung in the south. Chinese authorities framed the exercises as “Justice Mission 2025,” and mark the latest iteration of a series of Taiwan focused exercises aimed to practice joint operations, port blockades, sea-air control, and deterring external intervention while disrupting maritime and air traffic in ways that would impede Taiwan’s ability to sustain normal commerce under crisis conditions.

Importantly, Chinese writings on a “Joint Blockade Campaign” do not present this concept as part of a gradual economic warfare campaign that can increasingly take on military characteristics as the situation escalates. PLA sources describe a campaign that may open with large-scale missile strikes on ports and infrastructure, mining operations, and rapid efforts to establish sea and air control while staving off any outside attempts to interfere. In this framing, a blockade is a direct component of kinetic conflict, rather than an alternative. Even so, it is worth considering how investments in the ability to conduct a blockade during a direct conflict widen the range of options for China as they navigate the road from competition to crisis and conflict. Preparing their military for direct action such as a Joint Blockade Campaign paired with a lightening style assault marks a straightforward path to reunification, but it also enables forms of economic warfare that form complimentary parallel paths to the same end. Channeling Sun Tsu’s maxim that the supreme art of war is to defeat your enemy without fighting, China will recognize that there may be a path to victory through imposing economic asphyxiation. If Taiwan is going to resist China’s reunification efforts, they must prepare for the widely discussed decisive and overwhelming lightening campaign, but they must be ready to face the subtler threat of economic warfare as well.

Why economic warfare is so likely

China’s desire to unify Taiwan with the mainland is about far more than merely re-acquiring lost territory, blotting out a symbol of democratic resilience, or achieving a longstanding goal to reinforce the CCPs legitimacy. In a single stroke it is an opportunity to seize a structural pillar of the global economy, corner an immensely important maritime and information exchange route, and secure its ability to project power and maintain access to markets around the globe. While China’s massive military buildup includes enormous investments in amphibious warfare and air assault capabilities, an all-out attack to rapidly regain Taiwan risks a prolonged land battle that might destroy much of the island’s inherent value. By contrast, economic warfare can be an effective means by which China can avoid direct action against Taiwan and preserve much of the value already accrued by decades of global investment in Taiwanese critical technologies and trade infrastructure.

Economic warfare is also extremely flexible and scalable, presenting China with a set of options that can be adapted to fit the strategic and operational realities existing at the time of the attempted reunification, with opportunities to make adjustments as the situation evolves. This flexibility and scalability is best illustrated by categorizing economic warfare into four escalating tiers: trade embargo, police actions, quarantine, and blockade. Understanding these tiers and their intended goals is a critical first step in building resistance against them.2

The lowest tier, trade embargo, is already largely in place. Every day, China uses its massive economic and military influence to deter nations and corporations around the globe from establishing relationships with Taiwan, denying them access to modern military and economic technology that might help them resist Chinese influence. Having been in place for decades, this approach has blunted Taiwan’s economic development and contributed to significant social friction within a Taiwanese population that remembers the economic dynamism and the feeling of opportunity that resided in past generations of Taiwan’s citizenry. What China has yet to do but certainly could is present foreign companies ranging from McDonald’s to Disney to Boeing with a choice – if you do business with Taiwan, you cannot do business on the mainland. While such a move would hurt Beijing economically, the possibility of the PRC taking this route cannot be ruled out especially since in the past multi-national corporations have buckled under Beijing’s threats. Chinese leaders may calculate that profit driven corporations will bend to their demands if forced to do so.

The second tier of economic warfare is the “lawfare” approach, which is the declaration of an internal police action to seize or block critical supplies en route to Taiwan. This approach  is also already in practice, as China’s Taiwan Affairs Office declared in 2024 that, despite widespread recognition by the international community for decades, there is no such thing as Taiwan “prohibited” or “restricted” waters around the Taiwanese outlying islands of Kinmen and Matsu.3 The Chinese coast guard then issued orders granting the authority for CCG ships to board foreign vessels suspected of “illegally entering waters on Chinese jurisdiction” around these islands, and to detain foreign nationals for up to 60 days without trial if they are suspected of “endangering national security.”

While the detention of only a limited number of merchant vessels inbound to Taiwan might not seem impactful, Taiwan’s enormous reliance on imported Liquefied Natural Gas (LNG) to power its electric grid is such that these selective boardings have the potential to bring economic activity on the island nearly to a stop. Taiwan typically receives one to two LNG tanker arrivals per day, and LNG storage can sustain electricity consumption for only 10–14 days under crisis conditions, so stopping inbound LNG ships for several weeks would cause Taiwan to quickly burn through stockpiles. As LNG provides approximately 50% of the total energy produced for the electric grid, and roughly 40% of the island’s energy is earmarked for residential and service sector consumption, Taiwan’s industrial sector would bear the brunt of the shortages. Even if significant war-time austerity measures and energy rationing were put in place, semiconductor manufacturing requires nearly uninterrupted power, and it is highly unlikely Taiwan could continue in its role at the center of global microchip manufacturing under these conditions.

The third tier of escalating economic warfare options is best described as quarantine, and it exists in both de jure and de facto forms. In its formal and legal sense, a quarantine is a peace-time enforcement measure that typically requires a UN Security Council resolution to stop the transport of materials to or from a place, but which can be declared without such a resolution if the nation justifies the action as a measure of self-defense. The clearest historical precedent for such an action is the U.S. quarantine of Cuba during the 1960’s Cuban Missile Crisis, an attempt to keep Russian ships from moving nuclear weapons to the island. While China might pursue this course, declaring that the movement of certain classes of cargo to and from the island of Taiwan is contrary to their national security, they could likely achieve the same or similar ends through a hybrid legal and economic approach. This could begin with China declaring inspection zones or “maritime safety advisories” in the Taiwan Strait, discouraging shipping firms from entering, and using diplomatic and economic leverage to reinforce them.4 During the 2022 live fire drills, during which China first conducted missile tests that flew over Taiwan, insurers such as Lloyd’s of London temporarily raised war-risk premiums for accessing Taiwanese waters.5 As Taiwan relies almost entirely on commercial shipping instead of a nationally flagged and crewed merchant marine, these increased insurance premiums would largely freeze commercial shipments to and from the island until new insurance coverages could be negotiated.

The fourth and final category would be China’s use of blockade to threaten and potentially destroy traffic to and from Taiwan. This is an act of war that requires formal declaration to the international community, and would also likely coincide with military actions taken against portions or the entirety of the Taiwanese Navy and Air Force. The unique strategic distinction of blockade over quarantine is that there is no rule that a blockade is unlawful if it disproportionately impacts the civilian population, so long as some military advantage is also being gained. As such, food, medicine, energy, and other critical resource transportation can be shut off. 6 By some estimates, Taiwan would face critical shortages of energy and food within 14 to 21 days if its ports were closed.7 Shutting down the manufacturing sector and significant national food and energy rationing could buy Taiwan several additional months of resistance, but conditions would be severe. The United States and partners could attempt to resupply Taiwan’s food and medical stores by air, an approach China might be less likely to challenge, but airlift capacity is orders of magnitude too small to replace port throughput when it comes to serving energy needs.8

For Beijing, embargo, lawfare, quarantine, and blockade all represent potentially decisive options that can also be downplayed as shows of restraint when considered next to the outright invasion of Taiwan that it has been preparing for. For Taipei, while Taiwan’s defenses have long been oriented toward stopping amphibious assault across the western beaches, the equal if not more likely threat of maritime asphyxiation has been largely neglected.

To negate a strategy of economic warfare, Taiwan must play the lead role in defending its own autonomy. Modern technologies and good government policy offer new opportunities to create a more resilient society in the face of increasing maritime pressure. Some of these opportunities focus on military investments, but to build resilience against economic warfare, many of the most important decisions Taiwan needs to make are tied to purely civil issues. By focusing on these opportunities, Taiwan has an opportunity to peacefully and asymmetrically prevent China from checkmating them economically before western nations could come to their aid.

Building resilience

To defeat the overwhelming logic driving China to pursue victory through economic warfare, Taiwan must look inwards and eastward. Inward, towards resilience through renewable energy investments, fossil fuel stockpiles, and a renewed merchant marine, and eastward, toward its pacific coastline and under-developed ports there. Long neglected in defense planning, these investments may be among Taiwan’s most important untapped strategic assets.

The most direct route Taiwan has to build resilience has to do with overhauling the national energy production by reducing investments that create overreliance on LNG and heavily subsidizing other sources of energy. As a benchmark, Taiwan should aim to ensure that at least 75% of its current energy demand is available via means other than natural gas, thereby achieving energy independence for residential use, general commercial and government services, and limited industrial production.

Achieving this 75% benchmark requires an increase in non-LNG sources by approximately 11GW of daily production. Taiwan is already well on its way towards achieving these goals, with renewable and battery storage targets exceeding 11GW by 2030, but these increases do not take into account reductions in coal powered energy production over the same time period. With the threat of energy interdiction looming large, Taiwan should make every effort to increase these renewable energy targets, expedite their completion, and ensure that investments remain on track.

Industrial growth led by increased chip production and data center construction will challenge Taiwan’s political leadership’s attempts to prioritize renewable energy investments, as rapid growth in energy consumption from these sectors is being met today with plans to increase Taiwan’s LNG capacity. Taiwan should consider tethering any increase in LNG production capacity on the island to matching increases in renewables, coal, and fuel oils. In the renewables sector, prioritizing investments in rooftop solar and small-scale battery storage are particularly critical, as they represent the most resilient forms of energy Taiwan will have in the face of the more advanced stages of blockade. With regards to coal and fuel oils, rapid investments should be made in topping off and expanding stockpiles, and coal plants decommissioned as a part of Taiwan’s larger environmental efforts must be subsidized to be capable of being rapidly brought back online.

Taiwan’s internal investments in its merchant marine are the next major hurdle in achieving resilience in the face of economic warfare. Taiwanese companies own an enormous share of the world’s shipping vessels, but fewer than 30% of the crews that sail them are Taiwanese. Foreign flagging has drastically reduced operating costs and kept Taiwanese companies profitable and competitive but has resulted in a dramatic decline in Taiwan’s maritime workforce. In executing an economic warfare campaign, Beijing would likely exert diplomatic and economic pressure on foreign registries, insurers, ports operators, and labor pools in an effort to disrupt commercial shipping to the island. Taiwan and partner nations should therefore develop contingency frameworks for sustaining critical shipping operations, including the rapid re-crewing of essential vessels with Taiwanese or partner-nation personnel willing to operate in contested conditions.

The main case for investment in coastal infrastructure on the east side of Taiwan is that it asymmetrically increases the military difficulties China faces when creating a cordon around Taiwan. A deep-water port at Hualien and Taitung, hardened and connected by tunnel and rail through the mountains, would give Taiwan a second strategic coastline for energy imports. In the event of a non-firing blockade, these ports would force China to commit a much larger portion of its maritime forces to patrolling and boarding duties in the Philippine Sea, driving up the logistics footprint and reducing their availability for other tasking. Existing infrastructure already provides a foundation: Hualien hosts an active Air Force base and is connected to Taipei and Taichung via the Central Cross-Island Highway and North-Link Railway, both of which include tunnels through bedrock.9 In 2018, Taiwan’s CPC Corporation conducted feasibility studies for building an LNG terminal at Hualien to diversify energy imports away from Kaohsiung.10 The Japanese Ministry of Defense has also assessed Hualien and Su’ao as potential logistics nodes in a Taiwan contingency.11

The undersea and information dimensions are equally critical. Taiwan is connected to the world by 15 submarine internet cables, most of which currently land on its western coast.12 In 2023, two cables connecting Taiwan’s Matsu Islands to the main island were cut, likely by Chinese fishing vessels, disrupting communications for weeks.13 While increasing use of space based internet providers offers some increased resiliency, bandwidth projections over the next several years suggest that these services will only be able to handle approximately 10% of Taiwan’s peacetime levels of internet traffic.14 To ensure access to higher levels of bandwidth, US Naval Postgraduate School researchers have warned that ports should be integrated with maritime domain awareness (MDA) networks, seabed sonar arrays, and AUV patrol routes to monitor and defend vital seabed infrastructure.15 If deep-water eastern ports were built with adjacent cable landing stations and hardened underground control rooms, they could serve as both logistics hubs and digital fortresses.

Building eastern ports is a strategic reorientation that forces China to contest both the Strait and the Pacific approaches simultaneously.

Risks of Failing to Act

If Taiwan remains dependent on its western ports and shallow coastal infrastructure, the island could be cut off from the world long before an invasion fleet appears over the horizon. China will have re-ordered the global balance of power without firing a shot.

The first and most visible consequence would be a Chinese monopoly over the world’s most advanced chips. Taiwan Semiconductor Manufacturing Company (TSMC) controls about 92 percent of global production of leading-edge chips under 7 nanometers, according to the Semiconductor Industry Association and Boston Consulting Group, and 100% of chips under 2 nanometers.16 If Beijing asserted control, whether through occupation, coercion, or forced “reunification”, it would hold the world’s digital future in its hands. Even if Taiwan’s engineers sabotaged fabrication plants, simply removing Taiwan from global chip supply chains would cost the global economy up to $1 trillion within a year.17

The second consequence would be a dramatic shift in the military geography of Asia. With Taiwan under its control, China would be able to break through the First Island Chain and project power into the central Pacific.18 The People’s Liberation Army Navy (PLAN) could position aircraft, anti-ship missiles, and submarines on Taiwan’s eastern shoreline, directly overlooking the Miyako Strait and Bashi Channel, the two maritime gateways used by U.S. and Japanese forces to move between the East China Sea and Philippine Sea.19 From Taiwan, China could threaten Japan’s southern Ryukyu Islands, monitor U.S. submarines departing Guam, and exert pressure on the Philippines’ Batanes Islands at the northern tip of Luzon.20 It is no exaggeration to say that if Taiwan falls, the South China Sea becomes a Chinese lake, and the Western Pacific becomes contested water.

Finally, the fall or isolation of Taiwan would shatter confidence in U.S. security commitments across the Indo-Pacific. Tokyo, Seoul, Manila, Canberra, and European partners are watching not only what China does, but whether the United States allows it. In think tank simulations and classified defense discussions, Japanese and South Korean officials have privately warned that if Washington fails to defend Taiwan, their governments will consider acquiring nuclear weapons or making accommodations with Beijing.21

In short, the cost of inaction is not merely Taiwanese democracy. It is global technological stability, the military balance in the Indo-Pacific, and the credibility of U.S. led relationships that underpin peace.

Policy Recommendations

As the damage that an attempted Chinese reunification with Taiwan would cause to the global economy is assessed to exceed $1 Trillion USD within a year, solutions oriented around averting that outcome should be of a magnitude befitting of that danger, and should be a burden shared by the global community. A significant portion of those solutions should be oriented around deterrence, including investments by the United States, European, and Asian nations in military forces able to intervene in such a reunification attempt, but a maritime crisis in the Taiwan Strait will not be solved by deterrence alone. Geography cannot be negotiated, and Taiwan’s geography dictates that its survival depends on eastward connectivity, to the Pacific, to allied logistics, and to a hardened industrial and energy base. A forward-looking strategy must therefore treat energy investments, port construction, undersea infrastructure, and logistics resilience as the new frontier of deterrence. The following actions can anchor that strategy for Taiwan, the United States, and key allies.

For Taiwan

  • Increase renewable and battery storage capacity by at least 11GW as soon as possible and no later than 2030.
  • Ensure Taiwan retains the excess energy-generating capacity of all coal power plants brought offline by investing in programs to keep them maintained and staffed in a reserve capacity.
  • Require that all LNG electricity production increases are paired with renewable energy investments of equal scale.
  • Work with shipping companies to develop a plan to rapidly re-crew critical merchant ships with Taiwanese crew.
  • Construct deep-water, dual-use ports on the eastern coast, at Hualien, Taitung, or Su’ao, with at least 18–20 meters of draft, hardened breakwaters, underground fuel storage, and tunnel-linked rail and highway networks through the Central Mountain Range.22
  • Integrate ports with military infrastructure, including coastal anti-ship missile batteries, rapid runway repair units, and underground command centers resistant to missile strikes.
  • Establish maritime domain awareness (MDA) and seabed defense capabilities tied to port development: fixed sonar arrays, autonomous underwater vehicles (AUVs), and secured landing points for undersea cables and fuel pipelines.23

For the United States

  • Fund a Taiwan East Coast Resilience Initiative under the Pacific Deterrence Initiative (PDI) or Foreign Military Financing (FMF) to support port deepening, fuel infrastructure, seabed surveillance, and logistics 24
  • Conduct joint logistics and sealift exercises using Taiwan’s east coast ports between the U.S. and Taiwanese forces, including roll-on/roll-off ship operations and distributed maritime sustainment exercises.
  • Integrate Taiwan into the U.S. Indo-Pacific undersea surveillance network, linking sonar systems, unmanned underwater sensors, and cable monitoring platforms from Japan to Guam.
  • Pre-position fuel, medical supplies, and emergency power generators in Japanese ports such as Yonaguni, Ishigaki, and Okinawa for rapid deployment via the Bashi Channel.

For Japan, Australia, and Allied Partners

  • Form a trilateral U.S.–Japan–Australia infrastructure group to co-finance Taiwan’s east coast port construction, modeled after their 2022 Pacific Islands cable funding mechanism.25
  • Link Taiwan’s eastern ports with Japanese bases in Yonaguni and Okinawa to create a logistics corridor stretching from Kyushu to Hualien.
  • Deploy multinational maritime patrols to deter cable cutting and seabed sabotage, using technologies already tested by NATO in the North Sea after the Nord Stream explosions.26
  • Encourage selective participation from European partners with Indo-Pacific interests, particularly in port hardening, cable-laying, and underwater repair capabilities.

Be opportunistic in quietly reminding partner nations that long term acquiescence to China comes with a price. These measures are not simply about infrastructure; they are about time. Building Taiwan’s eastern ports, hardening its seabed cables, and securing its fuel lines will take years, but deterrence is measured in the credibility of what is already underway. The window to act is narrowing, and each year of delay leaves the island and the global economy more exposed to the whims of the strait.

Conclusion: The Eastward Imperative

Every strategy is ultimately shaped by geography, and no geography in the Indo-Pacific is more decisive than Taiwan’s location between the Strait and the Pacific. For decades, Taiwan, its partners, and even its adversaries have assumed that the island’s fate will be decided westward, across the Taiwan Strait. But the Strait is no longer a protective moat; it is a narrowing corridor easily sealed by missiles, naval patrols, and even insurance premiums. The waters that once carried Taiwan to prosperity now form the most vulnerable seam in its defenses. Taiwan’s endurance depends on building resilience at home and reorienting its future growth eastward.

This is not only a question for Taiwan. The entire global economy hinges on Taiwan’s autonomy, as the effects of reunification with China would be global: supply chains fractured, energy routes reoriented, and the balance of power in Asia permanently altered. But that future is not inevitable. Taiwan, the United States, Japan, and like-minded partners have the resources and time, though not unlimited time, to act. The construction of eastern ports is not merely an engineering problem; it is a strategic decision. It is the difference between a Taiwan that must be rescued and a Taiwan that can endure.

Joseph Hanacek is a Surface Warfare Officer in the United States Navy. He serves as a Warfare Tactics Instructor at the Surface Advanced Warfighting School detachment of the Naval Surface and Mine Warfighting Development Center in San Diego, CA. The views and opinions presented herein are those of the author and do not necessarily represent the views of the Department of War, the Department of the Navy, or its components.

Josh Richards is the Chief Commercial Officer of Pacific Peering. He serves on the UN’s Joint Task Force on SMART Cables as a member of the Steering Committee, and chairs the Business Development Committee. He is a Security Fellow with the Truman National Security Project, a Tech Policy Fellow with the Aspen Institute, and a Senior Fellow with AI2030. He received his MBA from National Chiao Tung University in Taiwan, spending a year in Hsinchu, headquarters to TSMC.

References

1. Yimou Lee and Yew Lun Tian, “China Launches Missiles Around Taiwan in Largest-Ever Drills,” Reuters, August 4, 2022, https://www.reuters.com/world/asia-pacific/suspected-drones-over-taiwan-cyber-attacks-after-pelosi-visit-2022-08-04/

2. Biggs, Adam; Xu, Dan; Roaf, Joshua; and Olson, Tatana (2021) “Theories of Naval Blockades and Their Application in the Twenty-First Century,” Naval War College Review: Vol. 74 : No. 1 , Article 9. https://digital-commons.usnwc.edu/nwc-review/vol74/iss1/9/

3. Record Number of Chinese Ships Enter Taiwan Waters Near Kinmen Island.” Radio Free Asia, May 10, 2024 https://www.rfa.org/english/news/southchinasea/china-kinmen-intrusion-05102024034553.html

4. Kathrin Hille and Demetri Sevastopulo, “China fires ballistic missiles around Taiwan after Nancy Pelosi’s trip,” Financial Times, August 2022, https://www.ft.com/content/15877208-4628-45fd-a8ff-2db7a3d57f1c

5. Lloyd’s List, “War Risk Insurance Premiums Rise Around Taiwan,” August 2022, https://www.lloydslist.com/-/media/lloyds-list/daily-pdf/2022/08-august/dailypdf090822.pdf

6. James Kraska, Raul Pedrozo, David Letts, Wolff Heintschel von Heinegg, Rob McLaughlin, James Farrant, Yurika Ishii, Gurpreet S. Khurana, and Koki Sato, The Newport Manual on the Law of Naval Warfare, vol. 101 of International Law Studies (Newport, RI: Stockton Center for International Law, 2023) https://digital-commons.usnwc.edu/ils/vol101/iss1/1/

7. CSIS, The First Battle of the Next War: Wargaming a Chinese Invasion of Taiwan, 2023, https://www.csis.org/analysis/first-battle-next-war-wargaming-chinese-invasion-taiwan

8. RAND Corporation, How to Succeed in Deterring an Invasion of Taiwan Without Really Trying (Hard), 2024, https://www.rand.org/pubs/commentary/2024/12/how-to-succeed-in-deterring-an-invasion-of-taiwan-without.html

9. Taiwan Highspeed Rail, Taiwan High Speed Rail Sustainability Report, 2022. https://en.thsrc.com.tw/Corp/9edfd684-60e2-4661-bf9e-bbbe1110b8b2/assets/28441302-5dfb-4206-9417-7d8e1e7cb34a.pdf

10. CPC Corporation (Taiwan), LNG Diversification Feasibility Study, Hualien, 2018. https://www.cpc.com.tw/en/cp.aspx?n=2720

11. Japan Ministry of Defense, Defense of Japan 2023 https://www.mod.go.jp/en/publ/w_paper/wp2023/DOJ2023_Digest_EN.pdf

12. TeleGeography, Submarine Cable Map, Taiwan, https://www.submarinecablemap.com

13. Global Taiwan Institute, “China’s Undersea Cable Sabotage and Taiwan’s Digital Vulnerabilities,” 2025 https://globaltaiwan.org/2025/06/taiwans-digital-vulnerabilities/

14. Joyu Wang, Micah Maidenberg, and Yang Jie, “Taiwan’s Race for Secure Internet Detours Around Musk’s Starlink,” Wall Street Journal, October 30, 2024 https://www.wsj.com/tech/taiwans-race-for-secure-internet-detours-around-musks-starlink-7c273912

15. Joseph Hanacek et al, Naval Postgraduate School, SEABED INFRASTRUCTURE DEFENSE ANALYSIS, 2019 https://calhoun.nps.edu/entities/publication/95ade676-aaa3-4d9e-a851-af0a3b9f5bb1

16. Semiconductor Industry Association (SIA) and Boston Consulting Group, Strengthening the Global Semiconductor Supply Chain, 2023, https://www.semiconductors.org/wp-content/uploads/2021/05/BCG-x-SIA-Strengthening-the-Global-Semiconductor-Value-Chain-April-2021_1.pdf

17. OECD, Vulnerabilities in the semiconductor supply chain, 2023, https://www.oecd.org/content/dam/oecd/en/publications/reports/2023/06/vulnerabilities-in-the-semiconductor-supply-chain_f4de7491/6bed616f-en.pdf

18. Andrew Erickson, “China Maritime Report No. 47: The People of China’s Navy and Other Maritime Forces,” China Maritime Studies Institute, US Naval War College, 2025 https://scholar.google.com/citations?view_op=view_citation&hl=en&user=sU-E-J0AAAAJ&sortby=pubdate&citation_for_view=sU-E-J0AAAAJ:kz9GbA2Ns4gC

19. U.S. Indo-Pacific Command, Posture Statement to Congress, 2024, https://www.armed-services.senate.gov/imo/media/doc/aquilino_statement.pdf

20. Japan Ministry of Defense, Defense of Japan, 2024, https://www.mod.go.jp/j/press/wp/wp2024/pdf/DOJ2024_Digest_EN.pdf

21. Michishita Narushige, Japan’s New National Security Strategy, CSIS, 2023 https://www.csis.org/analysis/japans-new-national-security-strategy

22. Ministry of Transportation and Communications (Taiwan), Hualien Port Expansion Report, 2022 https://www.motc.gov.tw/en/app/news_list/view?module=news&id=158&serno=ff894f74-a317-479a-8183-0228caeff0be

23. Joseph Hanacek et al, Naval Postgraduate School, SEABED INFRASTRUCTURE DEFENSE ANALYSIS, 2019 https://calhoun.nps.edu/entities/publication/95ade676-aaa3-4d9e-a851-af0a3b9f5bb1

24. U.S. Department of Defense, Pacific Deterrence Initiative Budget Overview, 2024 https://comptroller.war.gov/Portals/45/Documents/defbudget/FY2024/FY2024_Pacific_Deterrence_Initiative.pdf

25. Australian Department of Defence, Trilateral Infrastructure Partnership with Japan and the U.S., 2022 https://www.dfat.gov.au/international-relations/joint-statement-australia-us-ministerial-consultations-ausmin-2022

26. McNamara, E. M. “Reinforcing resilience: NATO’s role in enhanced security for critical undersea infrastructure.” NATO Review 28 (2024) https://www.dvidshub.net/audio/82211/nato-review-reinforcing-resilience-natos-role-enhanced-security-critical-undersea-infrastructure

Featured image: The Taiwan Innotech Expo Innovation Economy Pavilion, 2025. (Wikimedia Commons)

The Weapon of Frozen Assets: A New Instrument of Maritime Financial Warfare

By Valery Bonakhau

Financial warfare is conventionally understood as an instrument applied to declared, identifiable assets. Common tactics include freezing accounts, cutting off correspondent banking access, and market delisting of entities. The Hormuz conflict of March 2026 introduced a structurally distinct mechanism operating on none of those principles. What follows is an analysis of that mechanism — how it emerged, how it functions, and why existing maritime security frameworks are not adapted to recognize it.

Executive Summary

In March 2026, the Hormuz conflict introduced a financial warfare instrument that most strategic analysts have not yet identified. Not the oil price shock. Not the insurance premium surge. This new instrument was the systematic immobilization of cargo in transit as active leverage. At peak, approximately 140 million barrels of oil were rendered undeliverable in the Persian Gulf.

This constitutes a new class of coercive instrument distinct from sanctions and asset seizure which shall be termed the weapon of frozen assets. The weapon of frozen assets is defined as a condition in which a supply chain position becomes illiquid through the convergence of three independent constraint systems. No freezing authority issues an order. No asset is formally declared blocked. The system constructs itself empirically.

The Mechanism: Frozen Assets as Active Leverage

Conventional financial warfare operates on declared assets: accounts frozen by executive order, correspondent banking access removed, entities delisted. The target knows what has been frozen. The freezing authority controls the instrument. What emerged in March 2026 is structurally different.

The blocked assets are not declared. They are positional.

A positional asset is a contractual, logistical, or financial state that becomes unrealizable under specific conditions. A vessel at anchor awaiting Iranian permission is a positional asset. How many such vessels are waiting — UKMTO, Kpler, and Lloyd’s List count them. The fact is recorded. The mechanism is not. Monitoring systems see the symptom: the vessel is stationary. Why every possible exit is simultaneously blocked — without a single official order, without a sanctions list, without a formal prohibition — is a question they do not ask. This is why the weapon of frozen assets went unidentified.

A very large crude carrier (VLCC), a supertanker exceeding 200,000 deadweight tons, carrying two million barrels of Abu Dhabi crude in transit becomes an unrealizable asset the moment it cannot deliver cargo, cannot obtain war-risk coverage for forward transit, or return to port without losses exceeding the cargo value. Returning is not a neutral option as the vessel has already paid freight, fuel, and port fees. A reversal means a new charter back, penalties for breach of the delivery contract, and the loss of sums already paid. The operator had done everything correctly. The cargo was legitimate. The documentation was clean. None of that mattered.

This is the weapon of frozen assets, and countermeasures have not been found.

In any conflict, equipment and personnel losses are counted. Financial warfare produces losses of a different kind: 1,600 vessels at anchor, billions of dollars of cargo going nowhere, and tens of thousands of trapped mariners. Kpler records these losses via satellite.

However, losses are not the weapon but the consequence of its use.

The weapon is the mechanism that created them. Three systems operate simultaneously without a single official order: a permit regime, an insurance barrier, and legislative formalization. None of them formally blocks a vessel, but together they make forward progress impossible.

Jask & the Architecture of Asymmetry

The weapon of frozen assets functions only if Iran can credibly threaten Hormuz while maintaining its own export capability. Without that asymmetry, mutual blockade produces symmetric damage, and the weapon loses its leverage.

Forty years of sanctions were not wasted. Iran spent four decades preparing for this scenario. The scale of Iranian preparation was systematically underestimated by external analysts.

The centerpiece is Jask, Iran’s only oil export terminal located outside the Strait of Hormuz. Crude reaches Jask via the Goreh-Jask pipeline from Bushehr province. Kpler data shows the terminal’s first loading in the current conflict was on March 7, 2026: tanker Dore, 2 million barrels. Design capacity is 1 million barrels per day, and effective capacity is estimated by the EIA and Kpler at approximately 300,000 barrels per day. Inside the Gulf, Iran also operates smaller terminals at Lavan Island, Sirri Island, and Soroosh. These terminals are primarily for cargo top-ups and are typically unable to receive fully loaded VLCCs.

This asymmetry is not incidental. It is the structural condition that makes the weapon of frozen assets viable as a sustained instrument rather than a one-time escalation. Iran can impose transit uncertainty on all other operators while maintaining its own revenue flow. This is not mutual deterrence. It is a directional weapon.

The asymmetry gives Iran a sorting mechanism. States that acquiesce receive access. Adversaries pay an uncertainty premium. Those undecided find their exposure used as an argument for compliance.

There is one further dimension that external analysis has underweighted. Fortune reports that Iran is exploring rail shipments of petroleum products to China via the China-Iran freight corridor, a 5,300-kilometer route through Turkmenistan and Kazakhstan that cuts transit time from 30-40 days by sea to 14-15 days by land. The critical caveat is that railways cannot transport bulk crude oil on an industrial scale. The rail corridor handles petroleum products, petrochemicals, and high-value goods. It is a contingency channel, not a replacement for tanker volumes. Nonetheless, its existence means Iran has built redundancy into its trade architecture that was not present in any previous standoff.

The Insurance Architecture as Operationalization

Within the first week of the conflict, Lloyd’s of London syndicates sharply repriced Hormuz transit coverage. War-risk premiums reached 2.5% to 5% of hull value per transit — $10 to $14 million for a single VLCC voyage. The Lloyd’s Market Association confirmed on March 23, 2026 that insurance was not withdrawn outright and coverage remained technically available. However, at rates approximately sixty times pre-conflict levels, the practical effect was identical to withdrawal. Operators consistently report that the primary constraint is physical danger to crew. The insurance architecture amplified that constraint into a financial impossibility for most commercial transits.

New coverage was available only through the DFC (U.S. International Development Finance Corporation) reinsurance facility and only for U.S.-flagged vessels or vessels with U.S. commercial interests at premium levels that rendered most commercial transits economically unviable. The two-tier structure was partly a design choice and partly a capacity constraint that no one had modeled in advance. On April 3, DFC expanded the program to $40 billion, adding six new underwriters. There is little evidence of actual utilization. The mechanics of this structure and its limits are analyzed in detail in RUSI Commentary on April 2, 2026.

Iranian legislative action on Hormuz transit developed in stages. In late March 2026, the parliamentary National Security and Foreign Policy Commission approved a 12-article bill titled “Consolidation of Iran’s Sovereignty in the Strait of Hormuz” and forwarded it to the Presidium of the Majlis. On March 31, the commission chairman stated: “47 years of hospitality are over forever.” As of May 7, 2026, the bill has not yet passed a full plenary vote — but Tehran has not waited for the law to implement its provisions operationally.

On May 5, 2026, Iran launched the Persian Gulf Strait Authority (PGSA): an official body with a formal email address providing a single window for arranging transit authorization with the IRGC Navy. Vessels must complete a “Vessel Information Declaration” disclosing ownership, insurance, crew manifests, and intended routes before receiving a transit permit. CNN obtained the form from Lloyd’s List. Richard Meade, editor-in-chief of Lloyd’s List, stated that Iran had positioned the PGSA as “the only valid authority to grant permission to ships transiting the straits,” per AGBI. As Splash247 noted, the creation of the authority gives Iran’s toll regime a veneer of bureaucratic legitimacy but resolves none of its legal problems as the IRGC remains a U.S.-designated foreign terrorist organization.

The convergence of three conditions — permit-based transit access, insurance-conditioned financial viability, and legislative formalization — produced the situation described above. A vessel operator simultaneously facing a permit fee demand, a repriced insurance market, and a formally constituted Iranian transit authority has no commercially viable path forward. Remove any one of those three constraints and the trap does not hold at scale. As of this writing, all three remain in force.

In existing analytical literature, this mechanism has not been described as a distinct instrument. It is not a single mechanism. It is what occurs when three independently operating constraint systems act simultaneously.

The $2 Million Question: Sanctions Exposure

The closest historical analogy is the ongoing management of the Suez Canal. Egypt has collected billions for passage through a waterway that geography created and lawyers formalized. What Iran did in March 2026 is structurally near identical with one distinction: the Suez Canal Authority holds a legal mandate. The Iranian corridor does not.

The $2 million is not the central issue. The central issue is that someone paid it. That payment is the precedent.

According to verified Bloomberg data, the Islamic Revolutionary Guard Corps’ (IRGC) base rate is $1 per barrel of crude, which translates to $2 million per transit for a VLCC-class vessel. On April 2, the container vessel CMA CGM Kribi, flagged in Malta and operated by French carrier CMA CGM, became the first Western European-operated vessel to transit Hormuz since the conflict began. The payment mechanism has not been officially disclosed. That same day, France vetoed a UN Security Council resolution that would have authorized military reopening of the strait. The timing is not coincidental.

In a single day, Paris appears to have settled its transit terms and blocked the resolution that would have rendered those terms unnecessary. This is the first documented instance of a NATO member acting openly at variance with allied positions based on national commercial interest alone. The precedent was not set by Tehran. It was set by Paris.

Payments were routed in Chinese yuan or through stablecoins, cryptocurrencies pegged to fiat currency values. Not dollars. This is deliberate architecture. The IRGC has constructed a five-tier system that ranks flag states by degree of political alignment. Yuan-denominated transactions fall entirely outside the dollar clearing system. Stablecoins settle on blockchain rails, circumventing traditional bank intermediaries.

Secretary Bessent’s March 16 statement addressed oil flows, not payment flows. On March 20, OFAC issued General License U (GL U), authorizing transactions necessary for the delivery and sale of Iranian-origin crude loaded prior to March 20 through April 19. GL U addressed oil flows. No authority addressed payment flows at that time. Baker McKenzie analysis confirms GL U was the first OFAC general license broadly authorizing transactions involving Iranian-origin crude oil.

That gap has since been partially closed — but only for U.S. persons. On May 7, 2026, OFAC updated its FAQ, stating: “Payments to the government of Iran or the Islamic Revolutionary Guard Corps (IRGC), directly or indirectly, for safe passage through the Strait of Hormuz would not be authorized for US persons, including US financial institutions, or for US-owned or -controlled foreign entities.” For non-U.S. operators, the legal ambiguity persists. GL U itself expired on April 19, 2026 and was not renewed — Secretary Bessent announced on April 15: “We will not be renewing the general license on Iranian oil.” Financial institutions are left with a compliance question Washington has answered only partially.

Implications for Maritime Security Planning

The situation described above is a structural trap. Documentation was clean. Cargo was legitimate. Every obligation was met. Yet the environment developed a permit system with no legal foundation, an insurance market repriced beyond commercial viability, and a sanctions framework that no authority is applying consistently to non-U.S. operators.

Four implications follow that current maritime security frameworks do not yet account for:

First, the unit of analysis for financial warfare in maritime conflict is the position, not the asset. Existing frameworks are designed around declared, identifiable assets. The weapon of frozen assets operates on positions — contractual, logistical, and financial states that become impossible to exit under specific conditions. A vessel at anchor awaiting an Iranian permit does not trigger any standard financial warfare indicator. This category of exposure is invisible to frameworks built for a different instrument.

Second, the DFC facility has set a precedent. Beijing and Tehran will both model the DFC response as a baseline constraint on U.S. escalation tolerance. The template is now established, and one can only wonder how this precedent will impact future action in the Taiwan Strait, the South China Sea, or the Turkish Straits. The RUSI analysis of the first DFC cycle examines this in detail. France demonstrated the practical consequence: when transit access is available at a price, commercial interest overrides coalition position.

Third, the weapon is self-sustaining once deployed. It does not require active maintenance. The permit regime, the insurance repricing, and the legislative structure each reinforce the others. Dismantling any single layer does not dissolve the trap as the Project Freedom experience confirms.

Finally, the legal architecture is deliberately ambiguous for non-U.S. operators. Tehran has structured the toll regime to create maximum uncertainty for third-country shipping firms: pay and risk U.S. secondary sanctions or refuse and remain stranded. That ambiguity is not a design failure. It is the instrument.

Conclusion

On May 4, the United States launched Operation Project Freedom, deploying guided-missile destroyers, over 100 aircraft, and 15,000 service members to guide neutral vessels out of the Persian Gulf. The operation was paused within 48 hours. Only two vessels transited through the Gulf. Approximately 1,600 remain stranded with the IMO reporting approximately 20,000 mariners aboard nearly 2,000 vessels trapped in the Gulf. Pre-war traffic through Hormuz averaged 120 crossings per day. The same day Project Freedom was paused, Iran launched the Persian Gulf Strait Authority, a formal bureaucratic structure with an official email address, application forms, and a stated mandate to regulate all Hormuz transit. The convergence of three constraints that produced the weapon of frozen assets has not been dismantled. It has received institutional form and will continue to evolve the longer the situation in the Gulf continues.

Valery Bonakhau is an Independent Analyst in Dubai. He spent two decades in capital management across Commonwealth of Independent States (CIS) and United Arab Emirates (UAE) markets before transitioning to independent research. His work applies financial mechanism analysis to geopolitical forecasting, identifying the structural constraints that force political decisions before they occur.

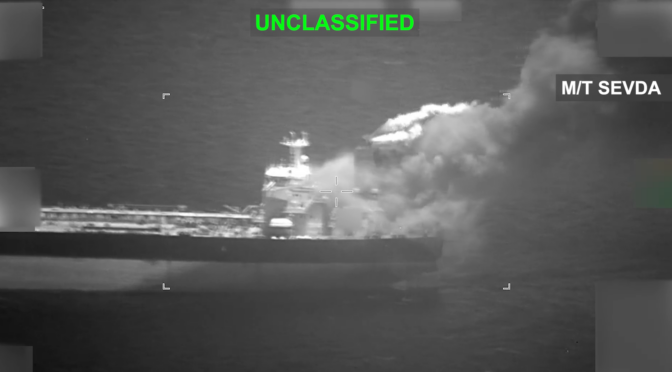
Featured Image: U.S. forces disabled M/T Sevda, an Iranian oil tanker, on May 8 prior to it entering an Iranian port on the Gulf of Oman in violation of the U.S. blockade of Iranian ports and the Strait of Hormuz. (U.S. Central Command photo)

Adam Smith Would Have Supported the Jones Act

By Michael D. Purzycki

Advocates of free trade often criticize the Jones Act as an unnecessary protectionist measure. Today, with inflation and supply chain weaknesses prominent in the news, the requirement for all cargo moving between American ports to be transported by U.S.-flagged ships strikes many as a senseless increaser of prices. Critics allege that the Jones Act makes intra-U.S. shipping “prohibitively expensive,”1 and call for “repeal or significant reform of this outdated law.”2 Why, they ask, should consumers pay higher prices so American sailors can protect jobs that foreign sailors could do just as well, for less money?

However, a strong case for the Jones Act can be found in the writing of one the first great advocates of the free market: Adam Smith. While he is remembered as the father of modern capitalism, he did not believe in market forces reigning supreme in every sector of the economy. One of the exceptions to his laissez-faire beliefs was the Navigation Acts, Britain’s equivalent of the Jones Act in Smith’s time, which he defended on national security grounds.

There is a lesson in Smith’s stance for the Jones Act’s critics. All sectors are not created equal – those that help support national security are different in importance, and different in the need for government intervention, from those that support private consumption. By giving American seafarers opportunities to practice their skills, the Jones Act helps the United States prepare for great power conflict. This is especially vital when Russia’s invasion of Ukraine has reminded the world how important NATO is to international security, and how vital it is for the U.S. to be ready to quickly defend its allies when they are attacked.

The Importance of the Merchant Marine

Passed in 1920, the Jones Act was intended to rectify a national security weakness that had emerged during World War I. As the Navy League has put it, “having realized the nation’s merchant fleet was not independently robust enough to neutralize German attacks,” Congress was determined not to allow such vulnerability in future conflicts.3 By making the transportation of cargo between domestic U.S. ports the preserve of American ships and their crews, it sought to give the U.S. Merchant Marine experience that would prove valuable during another major war.

If there were ever a situation in which the Merchant Marine proved its worth, it was World War II. Merchant mariners were the ones who brought American weapons, ammunition, and food to Britain in the face of Nazi U-boats. Their casualty rate was higher than any branch of the military, with 9,300 merchant mariners killed.4 But thanks to the Merchant Marine, when the Allies began to liberate Europe from Hitler, “[n]o Allied army was ever driven back from a hard-won beachhead for lack of supplies,” as TIME put it in 2016.5

Today, thanks to the Jones Act, the U.S. has “thousands of skilled mariners who, during surge sealift operations, can operate government-owned sealift vessels and provide supplemental crews on international fleet ships,” in the words of the Navy League.6 The act has endured for more than a century despite long-standing criticism from those whose belief in free trade trumps what value they might see in America’s sealift capability. For the sake of national and international security, it should be kept in place; however, many voices continue to clamor for its repeal.

When Free Trade Works

There are cases in which free trade makes geopolitical as well as economic sense. After World War II, the U.S. undertook the reconstruction of Western Europe and Japan, helping to ensure they would not fall into the Soviet orbit during the Cold War. It did this not only through direct funding efforts like the Marshall Plan, but by opening the American market to European and Japanese exports, helping to revive industrial bases devastated by the war. As Robert D. Atkinson and Michael Lind noted in American Affairs in 2019, when West German and Japanese industries began to gain ground against their American competitors, “the U.S. government looked the other way (or in some cases, provided active support for these policies), in the interest of a unified alliance against the Soviet Union.”7 Pairing NATO and the U.S.-Japan alliance with economic growth across the Atlantic and Pacific tightened the links between the U.S. and its allies in the struggle against communism.

Similarly, had the United States ratified the Trans-Pacific Partnership (TPP), today it would be standing at the head of a twelve-nation bloc making up 40% of the world’s GDP – including highly developed economies like Japan, Australia, Singapore, and Chile – while pointedly excluding China.8 The U.S. would be taking the lead in writing the rules of trade in the Pacific, rules serving the interests of American industries and workers rather than the Chinese Communist Party. Instead, since the U.S. abandoned the TPP, a successor agreement has emerged – one that China now seeks to join.9

The value of excluding China points to the need for a national security exception to free trade. While Vladimir Putin’s war in Ukraine has understandably focused the world’s attention on eastern Europe, a Chinese invasion of Taiwan, or a Chinese attack on Japan, is a continuous possibility. When conflict with rival great powers is on policymakers’ minds, sealift capability should be, too. If the U.S. cannot get its troops and their supplies to the front, it will be at a disadvantage. A country unable to protect its vital interests is a country unable to enjoy the benefits of international trade.

Can the U.S. Do Sealift?

Today, America’s ability to bring its forces and supplies to battle is far from certain. In January 2020, Rear Admiral Mark Buzby told the Surface Navy Association Symposium that, in a September 2019 exercise to test the Ready Reserve Force’s ability to sail on short notice, only about 40% of the vessels involved proved ready to leave port.10 This is a troubling statistic at a time when the U.S. may have to rapidly move personnel and equipment across the Atlantic to protect NATO allies from Putin’s forces.

Meanwhile, an October 2020 report by CNA on COVID-19’s effects on seafarers around the world, described “despair in the US Merchant Marine.” It was unclear whether Military Sealift Command’s (MSC) “Gangways Up” policy, keeping mariners on their ships to protect them from the pandemic, was truly “balancing the health of the fleet with the wellbeing of the mariners.”11 Mariners’ health should be factored into discussions of the Jones Act. If the crews who transport troops and equipment are not physically or mentally healthy, even vessels ready to set sail may not be of much use.

These vulnerabilities coincide with the relatively low priority the U.S. places on military sealift. At a February 2022 conference of the National Defense Industrial Association, Eric Labs, a naval analyst at the Congressional Budget Office, described sealift as the “black sheep” of shipbuilding.12 Even though sealift vessels move about 90% of Army and Marine Corps combat equipment and supplies, less than two percent of the Navy’s shipbuilding budget is being allocated to sealift platforms.13 If low investment in vessels is paired with the U.S. undermining the crews needed to man those vessels, American sealift could be doubly weakened when the country needs it.

Britannia Ruled the Waves

When 17th century England sought to become the world’s preeminent sea power, it understood the importance of a nation’s hard power to its trade. Beginning in 1651, the Navigation Acts sought to ensure England had a robust maritime workforce. The first act, passed during England’s brief period as a commonwealth after the execution of King Charles I, read:

“…no Goods or Commodities whatsoever, of the Growth, Production or Manufacture of Asia, Africa or America, or of any part thereof…as well of the English Plantations as others, shall be Imported or brought into this Commonwealth of England, or into Ireland, or any other Lands, Islands, Plantations or Territories to this Commonwealth belonging, or in their Possession, in any other Ship or Ships, Vessel or Vessels whatsoever, but onely in such as do truly and without fraud belong onely to the People of this Commonwealth, or the Plantations thereof, as the Proprietors or right Owners thereof; and whereof the Master and Mariners are also for the most part of them, of the People of this Commonwealth”14

After the monarchy was restored in 1660, King Charles II continued the policy. The second Navigation Act, passed in the first year of his reign, stated:

“…noe Goods or Commodities whatsoever shall be Imported into or Exported out of any Lands Islelands Plantations or Territories to his Majesty belonging or in his possession or which may hereafter belong unto or be in the possession…in any other Ship or Ships Vessell or Vessells whatsoever but in such Ships or Vessells as doe truely and without fraude belong onely to the people of England…or are of the built of, and belonging to any of the said Lands Islands Plantations or Territories as the Proprietors and right Owners therof and wherof the Master and three fourthes of the Marriners at least are English.”15

This was, as James Fallows noted in a 1993 Atlantic article comparing different philosophies of trade, “blatantly protectionist legislation.”16 At first glance, these laws appear likely to alienate an advocate of the free market like Smith. And yet, the patron saint of capitalism supported them.

Smith’s National Security Exception

In his 1776 magnum opus, An Inquiry into the Nature and Causes of the Wealth of Nations, Smith wrote:

“The defence of Great Britain, for example, depends very much upon the number of its sailors and shipping. The act of navigation, therefore, very properly endeavours to give the sailors and shipping of Great Britain the monopoly of the trade of their own country, in some cases, by absolute prohibitions, and in others, by heavy burdens upon the shipping of foreign countries.”17

And:

“As defence, however, is of much more importance than opulence, the act of navigation is, perhaps, the wisest of all the commercial regulations of England.”18

There is a sense in which Smith’s position should not be especially surprising. His book is, after all, about the economic strength of nations, not individuals or corporations. Given his understanding of the need for geopolitical power to protect trade, it makes sense that he would favor British seafaring strength over market forces when the two conflicted.

America’s strength and prosperity, like Britain’s before it, has always depended on maritime power. Like the Royal Navy in the 18th and 19th centuries, the United States Navy is the ultimate guarantor of its country’s preeminence on the world stage, both economically and politically. And like Smith’s Britain, today’s America requires a capable maritime workforce, one that can regularly exercise its skills, so it is prepared for war when the time comes.

Follow Smith’s Example

At a time of high inflation, it is understandable that consumers and their representatives would look for any possible way to lower prices. But quickly putting more money into people’s pockets is not the only aim of public policy with a maritime component. National security, including the ability of a country to win conflicts and protect its interests abroad, makes national prosperity possible in the long term – and conflicts like the current war in Ukraine show just how vulnerable economic forces are to the military power of America’s rivals.

As a superpower whose closest allies are oceans away, the U.S. must always be able to bring its troops and their supplies quickly across those oceans to its allies’ defense. The current threat of Russia, and the long-term threat of China, should focus policymakers’ attention on sealift capability. Keeping the Merchant Marine in good working order is in America’s interest, even if it raises prices a little. In the spirit of Adam Smith, and his nuanced understanding of markets and security, the U.S. should keep the Jones Act in place.

Michael D. Purzycki is an analyst, writer, and editor based in Arlington, Virginia. He has worked for the United States Navy, Marine Corps, and Army. In addition to CIMSEC, he has been published in Divergent Options, Merion West, the Washington Monthly, Wisdom of Crowds, Charged Affairs, Braver Angels, and more. He can be found on Twitter at @MDPurzycki and on Medium at https://mdpurzycki.medium.com/. The views expressed here are his own.

References

1 The Editors. “Supply-Chain Crisis Isn’t Going Away.” National Review, December 15, 2021. https://www.nationalreview.com/2021/12/supply-chain-crisis-isnt-going-away/#slide-1

2 Grabow, Colin, and Inu Manak. “The Case against the Jones Act.” Cato Institute, June 2020. https://www.cato.org/books/case-against-jones-act

3 Navy League of the United States. “China’s Use of Maritime for Global Power Demands a Strong Commitment to American Maritime.” November 2020. https://navyleague.org/wp-content/uploads/2020/11/2020_Jones-Act_digital.pdf

4 Geroux, William. “The Merchant Marine Were the Unsung Heroes of World War II.” Smithsonian Magazine, May 27, 2016. https://www.smithsonianmag.com/history/merchant-marine-were-unsung-heroes-world-war-ii-180959253/

5 Geroux, William. “World War II Shows Why We Need the Merchant Marine.” TIME, April 21, 2016. https://time.com/4303121/world-war-ii-merchant-marine/

6 Navy League of the United States. “China’s Use of Maritime for Global Power Demands a Strong Commitment to American Maritime.” November 2020. https://navyleague.org/wp-content/uploads/2020/11/2020_Jones-Act_digital.pdf

7 Atkinson, Robert D., and Michael Lind. “National Developmentalism: From Forgotten Tradition to New Consensus.” American Affairs, Summer 2019. https://americanaffairsjournal.org/2019/05/national-developmentalism-from-forgotten-tradition-to-new-consensus/

8 Granville, Kevin. “The Trans-Pacific Partnership Trade Accord Explained.” New York Times, July 26, 2016. https://www.nytimes.com/2016/07/27/business/international/the-trans-pacific-partnership-trade-accord-explained.html

9 Reuters. “China applies to join Pacific trade pact to boost economic clout.” September 17, 2021. https://www.reuters.com/world/china/china-officially-applies-join-cptpp-trade-pact-2021-09-16/

10 Werner, Ben. “Test of Ready Reserve Force Exposes Need For Newer Ships, More People.” U.S. Naval Institute, January 16, 2020. https://news.usni.org/2020/01/16/test-of-ready-reserve-force-exposes-need-for-newer-ships-more-people?utm_source=USNI+News&utm_campaign=b5cddb026e-USNI_NEWS_DAILY&utm_medium=email&utm_term=0_0dd4a1450b-b5cddb026e-234331785&ct=t(USNI_NEWS_DAILY)&mc_cid=b5cddb026e&mc_eid=bf408583f1

11 Tallis, Joshua, Cornell Overfield, Kevin Inks, and Cherie Rosenblum. “Adrift: COVID-19 and the Safety of Seafarers.” CNA, October 2020. https://www.cna.org/CNA_files/PDF/CSI-2020-U-028490-Final.pdf

12 Harper, Jon. “Military Sealift Considered ‘Black Sheep’ of Shipbuilding Family.” National Defense, March 25, 2022. https://www.nationaldefensemagazine.org/articles/2022/3/25/military-sealift-considered-black-sheep-of-shipbuilding-family

13 Ibid

14 “An Act for increase of Shipping, and Encouragement of the Navigation of this Nation.” https://www.british-history.ac.uk/no-series/acts-ordinances-interregnum/pp559-562

15 “An Act for the Encourageing and increasing of Shipping and Navigation.” https://www.british-history.ac.uk/statutes-realm/vol5/pp246-250

16 Fallows, James. “How the World Works.” Atlantic, December 1993. https://www.theatlantic.com/magazine/archive/1993/12/how-the-world-works/305854/

17 Smith, Adam. “An Inquiry into the Nature and Causes of the Wealth of Nations.” https://www.gutenberg.org/files/3300/3300-h/3300-h.htm

18 Ibid

Featured Image: A large banner bearing “Jones Act” is featured on a large container ship (Credit: Kendra Seymour).